5 Home Loans for Single Moms: Mortgage Options and How to Qualify
Buying a home as a single mother often means qualifying with one income, managing a down payment, and comparing programs carefully. The best home loans for single moms are usually...
Quincy D.-Sep 22, 2026
Photo by TAG Mobile
Table of Contents
Buying a home as a single mother often means qualifying with one income, managing a down payment, and comparing programs carefully. The best home loans for single moms are usually not parent-specific products but mortgages with lower down payments, flexible underwriting, or local assistance. Reviewing FHA, conventional, USDA, VA, and state programs can help identify financing that better fits your budget.
1. Are There Home Loans for Single Moms?
Yes. Single mothers can qualify for the same mortgage programs available to other eligible buyers, including FHA, conventional, USDA, VA, and state or local assistance options.
Qualification usually depends on income, credit, debt, savings, property type, and program rules rather than single-parent status alone.
2. How Do 5 First Time Home Buyer Loan Options Compare?
Different loan programs solve different homebuying challenges, from low down payments to rural financing or military benefits.
Comparing eligibility, upfront costs, mortgage insurance, and income requirements can help single mothers choose a program that matches their financial situation.
FHA Loans
FHA loans are insured by the Federal Housing Administration and are known for lower down-payment requirements and more flexible credit qualification than many conventional mortgages.
Qualified borrowers may put down as little as 3.5% of the purchase price.
For buyers researching home loan grants for single moms, FHA financing can also work with eligible gifts, second mortgages, and down-payment assistance programs.
Conventional Loans
Conventional mortgages are not backed by a federal agency, but affordable options such as Fannie Mae HomeReady and Freddie Mac Home Possible can require as little as 3% down.
Both programs are designed for qualifying lower-income borrowers and can accept certain grants or other approved funding sources toward upfront costs.
For 2026, HomeReady and Home Possible generally use an income limit of 80% of the area median income.
Approved lenders can offer 100% financing, meaning qualified borrowers may purchase without a down payment. Income limits, property location, and lender underwriting still apply.
VA Loans
VA-backed home loans are available to eligible veterans, service members, and certain surviving spouses.
The VA generally does not require a down payment, and VA-backed purchase loans do not require private mortgage insurance, which can significantly reduce upfront and monthly housing costs.
Some borrowers may still pay a VA funding fee unless exempt, along with applicable closing costs.
State and Local Mortgage Programs
States, cities, counties, and housing finance agencies may offer down-payment assistance, affordable mortgages, or other homeownership programs for lower-income and first-time buyers.
Programs vary significantly by location, so eligibility should be checked locally. USAGov also warns that the federal government does not simply provide “free money” to individuals to purchase homes, making legitimate program verification important.
Single moms may qualify for home loans for single moms and homebuyer assistance programs. (Image by Unsplash)
Single-income buyers need to look beyond the headline interest rate because monthly affordability depends on debt, fees, insurance, and cash required at closing.
When comparing home loans for low income single moms, standardized loan estimates from multiple lenders make side-by-side evaluation much easier.
Compare Your Debt-to-Income Ratio
Start by reviewing how much of your monthly income already goes toward debts such as credit cards, auto loans, or student loans.
Lenders use debt-to-income calculations when evaluating affordability, so reducing existing balances can strengthen your position before applying.
Request Multiple Loan Estimates
Ask several lenders for loan estimates based on the same loan type and similar terms. CFPB recommends comparing multiple offers because the standardized form shows interest rate, monthly principal and interest, closing costs, and other charges in a format that is easier to evaluate.
Compare Cash Needed at Closing
A lower monthly payment does not automatically mean a better deal if the loan requires much more cash upfront.
Review the down payment, lender fees, points, and prepaid costs before deciding which offer fits your savings.
Look Beyond the Interest Rate
Two offers with similar rates can still have very different total costs because of fees, mortgage insurance, points, or lender credits.
CFPB specifically recommends comparing the loan amount, interest rate, monthly payment, and lender-controlled costs rather than judging offers by one number alone.
Check Whether the Rate Is Locked
Mortgage rates can change before closing unless the lender has locked the rate for a specified period.
Review the first page of each loan estimate to see whether the rate is locked and until when, especially when comparing offers received on different dates.
4. Could a Lower Phone Bill Help You Save for a Home?
Reducing recurring expenses can free up more room for a down payment, emergency fund, or future mortgage costs.
Phone service may be one area where eligible households can lower monthly spending without giving up essential communication.
Lifeline is a federal benefit that helps qualifying low-income households reduce the cost of phone or internet service. TAG Mobile participates in the program and currently offers no-monthly-cost wireless service for eligible customers, with up to 16GB of free monthly data, unlimited talk and text, and international calling.
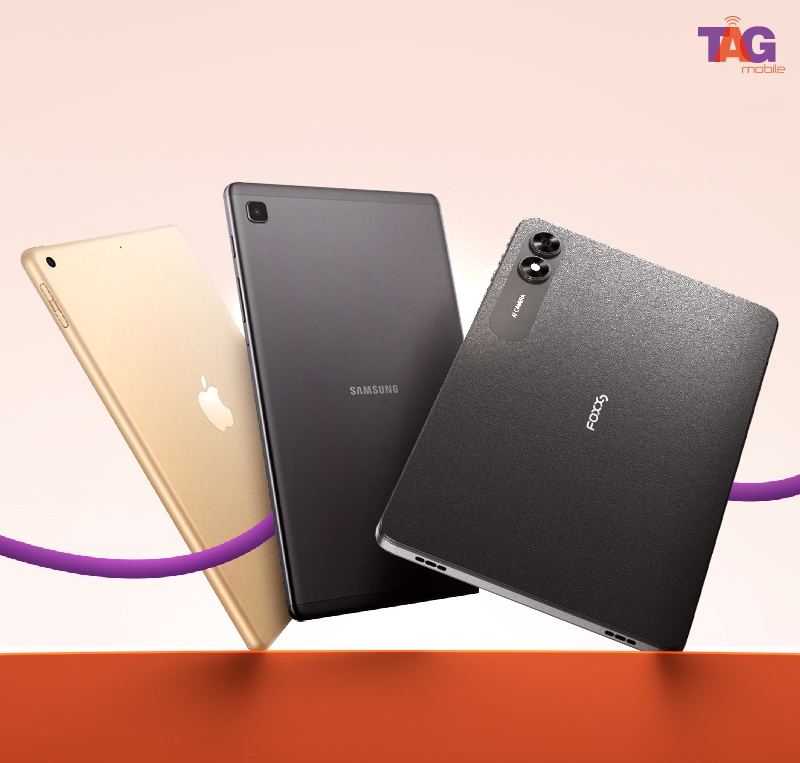
TAG Mobile may also offer free or discounted devices to eligible customers, depending on location and availability. These device offers are provided by TAG Mobile and are separate from the Lifeline benefit itself.
iPhone XS: Apple smartphone suited to calling, messaging, FaceTime, browsing, email, banking apps, and other everyday iOS tasks.
Samsung Galaxy S21+ 5G: 5G-capable Samsung smartphone with strong performance for multitasking, video calls, streaming, photography, and everyday app use.
TCL 20 SE: Large-screen Android smartphone that works well for browsing, video viewing, messaging, and regular mobile tasks.
Samsung Galaxy A32 5G: 5G Android smartphone suited to communication, media, browsing, and general daily use for customers who prefer Samsung devices.
Exact device pricing and availability can vary by ZIP code, eligibility, and inventory, so customers should check each product page before applying.
Explore the device list on TAG Mobile. Do note that stock can change and vary by state.
Note: Eligibility varies by state and program. Offers depend on availability and qualifications. TAG Mobile operates under the federal Lifeline Program as an Eligible Telecommunications Carrier (ETC). Service is non-transferable and limited to one service per household.
5. FAQs about Home Loans for Single Moms
Mortgage options can vary widely depending on income, credit, savings, debt, and the type of assistance available locally.
Can a single mom buy a house on one income?
Yes. A single mother can qualify for a mortgage using one income if it is sufficient to meet the lender’s requirements for debt-to-income ratio, credit, employment history, and cash needed at closing.
Are there first time home buyer loans for single moms?
Yes, but most programs are not limited specifically to single mothers. FHA, HomeReady, Home Possible, USDA, VA, and state or local first-time buyer programs may all be worth exploring if the borrower meets their individual eligibility rules.
Can down-payment assistance be combined with a mortgage?
Often, yes. Many state and local assistance programs are designed to work alongside FHA, conventional, USDA, or other eligible mortgages.
What are home loans for single moms with bad credit?
This phrase usually refers to mortgage options that may accept lower credit scores or more flexible underwriting, not a special loan created only for single mothers. FHA loans and certain local programs may be more accessible, but income, debt, down payment, and lender requirements still apply.
6. Final Thoughts
Buying a home on one income becomes more manageable when the loan program, monthly payment, and upfront costs all fit the same budget. Comparing home loans for single moms across FHA, conventional, USDA, VA, and local assistance options can reveal more realistic paths to ownership. Down-payment support may further reduce the initial burden. TAG Mobile can also help eligible households lower recurring wireless costs through Lifeline-supported service.
Share
TAG Blog
Stories, guides, and helpful updates for staying connected.