13 Single Mom First-Time Home Buyer Grants and Assistance Programs
Purchasing a home on a single income can feel daunting, particularly when managing initial down payments and closing fees. Exploring single mom first-time home buyer grants can sig...
Quincy D.-Sep 28, 2026
Photo by TAG Mobile
Table of Contents
Purchasing a home on a single income can feel daunting, particularly when managing initial down payments and closing fees. Exploring single mom first-time home buyer grants can significantly ease these upfront expenses and make homeownership more accessible.
1. Are There Really First Time Home Buyer Grants for Single Moms?
Yes. Homebuying assistance exists, but most programs are not reserved only for single mothers.
Eligible buyers may receive different forms of homebuying assistance based on factors such as income, location, occupation, and first-time buyer status.
2. 13 Great Homebuyer Programs for Single Moms
Homebuying assistance comes in several forms, so not every option below is technically a grant.
Some provide nonrepayable funds, while others use loans, discounted homes, flexible financing, or local assistance to reduce upfront costs.
Bank of America Down Payment Grant + America’s Home Grant
Bank of America currently offers two homebuyer grant programs in select markets.
Its Down Payment Grant provides up to 3% of the purchase price, capped at $10,000, while America’s Home Grant provides up to $7,500 toward eligible nonrecurring closing costs or a permanent rate buydown. Neither grant requires repayment.
For buyers comparing single mom first-time home buyer grants, these programs can significantly reduce upfront costs when property, borrower, and market requirements are met.
Chenoa Fund Down Payment Assistance
Chenoa Fund provides down-payment assistance through CBC Mortgage Agency and can be paired with qualifying FHA financing. Current options include 3.5% or 5% assistance structured as either a repayable or forgivable second mortgage.
This is not automatically free grant money. Forgiveness depends on program terms, including qualifying on-time mortgage payments, so borrowers should review the second-mortgage structure carefully before closing.
National Homebuyers Fund Down Payment Assistance
The National Homebuyers Fund offers down payment and closing cost assistance through participating mortgage lenders.
The organization reports supporting more than 72,000 households and providing over $672 million in down-payment assistance over its operating history.
Assistance structure, mortgage type, income limits, and availability can vary.
Single mothers should ask an approved lender whether the current NHF option is a grant, forgivable assistance, or repayable financing in their situation.
State Housing Finance Agency DPA Programs
Every state has a housing finance agency created to address local affordable-housing needs.
These agencies commonly offer first mortgages, down-payment assistance, closing-cost support, or programs designed for low- and moderate-income buyers.
When researching single mom first time home buyer grants, state HFAs are one of the most important places to check because eligibility and benefits are tailored to local housing markets rather than one national standard.
HUD specifically allows CDBG funds to support eligible homeownership assistance, although local governments decide how their allocations are used.
That means assistance may take different forms depending on how the local government uses its CDBG allocation. Availability depends entirely on your city or county.
Fannie Mae Community Seconds
Community seconds are subordinate mortgages that can help cover all or part of a down payment and closing costs.
They may be offered by governments, housing finance agencies, nonprofits, employers, or other approved sources and can sometimes be combined with Fannie Mae mortgages.
These are not automatic grants because repayment terms vary. Repayment terms vary by provider, so review the second-lien requirements before accepting the assistance.
Fannie Mae HomeReady
HomeReady is a conventional mortgage designed for lower-income borrowers and allows down payments as low as 3%.
It also accepts multiple funding sources, including eligible grants, gifts, and Community Seconds, which can reduce the amount buyers need to provide from their own savings.
HomeReady itself is not one of the first time home buyer single mom grants, but it can work alongside assistance programs and may offer more flexibility than a standard conventional mortgage.
Participants generally must be first-time homeowners, meet minimum-income requirements, and complete housing counseling.
Not every public housing agency offers this option. Single mothers already receiving voucher assistance should contact their local PHA directly to ask whether a homeownership program currently operates in their area.
Public Housing Agency Homeownership Programs
Some public housing agencies operate additional homeownership programs for eligible public-housing residents.
HUD rules allow certain homeownership initiatives to provide assistance with home purchases, but availability and funding depend on the individual PHA.
Availability is highly local, so this should not be treated as a universal benefit. Contact the PHA managing your current housing to ask whether homeownership assistance is offered.
HUD Good Neighbor Next Door
HUD’s Good Neighbor Next Door program offers eligible teachers, law enforcement officers, firefighters, and emergency medical technicians a 50% discount on certain HUD-owned homes in designated revitalization areas.
Buyers must generally occupy the home as their principal residence for 36 months.
The discount is secured through a silent second mortgage during the occupancy period.
Property availability is limited and changes frequently, so this option suits only buyers who meet both occupation and property requirements.
USDA Rural Homeownership Programs
USDA Rural Development offers homeownership programs for qualifying buyers in eligible rural areas.
Options include direct loans for lower-income applicants and guaranteed loans through approved lenders, with some programs allowing 100% financing and no traditional down payment.
These programs are loans rather than grants, but they can reduce one of the biggest barriers to buying: upfront cash. Income and property-location rules still apply.
Native American Direct Loan
The VA Native American Direct Loan program helps eligible Native American veterans and qualifying spouses buy, build, or improve homes on eligible Federal Trust Land.
Current benefits include no down payment, no private mortgage insurance, low closing costs, and direct VA financing.
Eligibility requires a valid VA Certificate of Eligibility and an eligible trust-land arrangement, including the required agreement between VA and the relevant tribal or governing authority.
Local HOME, City, or County Homebuyer Assistance
Cities, counties, and local housing agencies often use federal and local funding to create homebuyer assistance programs tailored to their communities.
Because the exact structure varies, search your city or county housing department rather than assuming every program is a grant. Some local assistance programs can be combined with eligible mortgage products.
3. How to Get the Most Single Mom First-Time Home Buyer Grants?
Strong applications usually come from comparing several assistance sources instead of relying on one program.
With single mom first-time home buyer grants, the biggest opportunities often appear when local assistance, affordable financing, and careful preparation are combined.
Check state and local programs first: Housing finance agencies, cities, and counties often have assistance that does not appear prominently in national searches.
Compare grants with forgivable loans: True grants require no repayment, while forgivable assistance may require you to remain in the home for a certain period.
Ask whether programs can be combined: Some buyers can pair down payment assistance with FHA, HomeReady, or other eligible mortgages.
Complete homebuyer education early: Many programs require counseling or education, and finishing it before applying can prevent delays.
Keep income and household documents ready: Tax returns, pay stubs, bank statements, benefit records, and identification are commonly required.
Improve credit and lower debt where possible: Better credit and a lower debt-to-income ratio can expand mortgage choices even when assistance covers part of the upfront cost.
Apply beyond programs labeled for single mothers: Parenting status alone rarely determines eligibility, so include first-time buyer, low-income, occupation-based, rural, and local programs in your search.
Read repayment terms carefully: Down-payment assistance can have different repayment terms, so review the applicable requirements before accepting it.
How to make the most of first time home buyer grants for single moms? Combine local grants, affordable financing, and careful preparation to maximize first-time homebuyer assistance. (Image by Unsplash)
4. How Can Combining Programs Save More Money?
Homeownership assistance can lower upfront costs, while other benefit programs may help reduce recurring household expenses.
Combining eligible support strategically may leave more room in the budget for mortgage payments, utilities, insurance, repairs, and everyday needs.
Lifeline is a federal benefit that reduces the cost of qualifying phone or internet service for eligible low-income households. It focuses on monthly communication service rather than providing the device itself.
You can generally qualify in two ways:
Income-based eligibility: Household income is at or below 135% of the Federal Poverty Guidelines.
Program-based eligibility: You or someone in your household participates in an approved program such as SNAP, Medicaid, SSI, Federal Public Housing Assistance, Veterans Pension or Survivors Benefit, or certain Tribal programs.
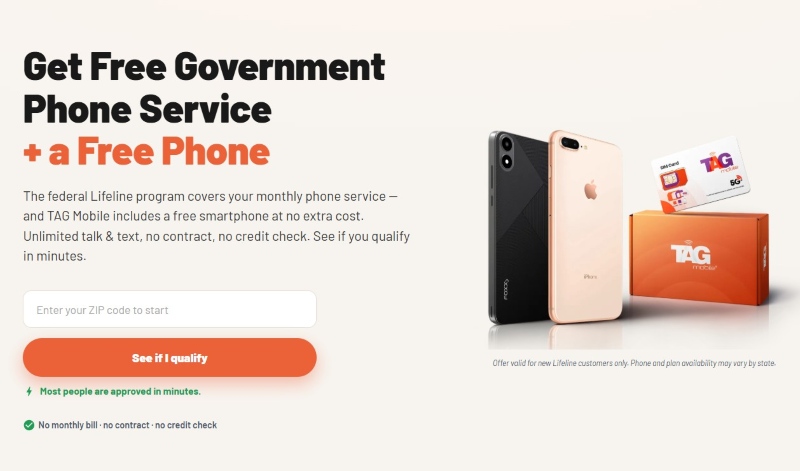
TAG Mobile is an eligible telecommunications carrier that delivers Lifeline-supported wireless service to qualifying customers.
Lifeline provides the service benefit, while TAG Mobile may offer qualifying applicants free or discounted devices along with communication features such as unlimited talk and text, free monthly data, and international calling to 200+ countries and territories, depending on location and plan availability.
As an Eligible Telecommunications Carrier, TAG Mobile provides Lifeline-supported free phone services to eligible customers.
Note: Eligibility varies by state and program. Offers depend on availability and qualifications. TAG Mobile operates under the federal Lifeline Program as an Eligible Telecommunications Carrier (ETC). Service is non-transferable and limited to one service per household.
5. Final Thoughts
Owning a home can become more attainable when the right financial assistance is matched with a realistic budget and long-term plan. Single mom first-time home buyer grants can help reduce down payments, closing costs, or other upfront expenses, while additional benefit programs can ease monthly bills.
TAG Mobile also gives eligible households another way to cut communication costs through Lifeline-supported service and available device offers.
Share
TAG Blog
Stories, guides, and helpful updates for staying connected.