Housing Grants for Single Moms Can Help With Rent, Homebuying, and More
Rent, utilities, and homebuying expenses can place significant pressure on a single-income household. Housing grants for single moms may include down payment assistance, rental sup...
Quincy D.-Sep 22, 2026
Photo by TAG Mobile
Table of Contents
Rent, utilities, and homebuying expenses can place significant pressure on a single-income household. Housing grants for single moms may include down payment assistance, rental support, local housing initiatives, and nonprofit programs for eligible families.
Because requirements vary, checking income limits and program rules can help narrow down the options that match your housing needs.
1. Are There Really Housing Grants for Single Moms?
Yes. Housing assistance is available through federal and local programs, although most options are based on income and housing need rather than single-parent status alone.
Single mom housing assistance may help with rent, down payments, utilities, or other eligible housing expenses.
2. Which Rental Assistance Programs Support Single Moms?
Rental support usually comes through broader low-income housing programs rather than grants reserved specifically for single mothers.
Housing Choice Voucher Program (Section 8)
The Housing Choice Voucher Program, commonly known as Section 8, helps eligible low-income households reduce rental costs in privately owned housing.
Local public housing agencies determine eligibility, and approved families typically pay part of the rent while the program covers the remaining eligible portion.
For single mothers exploring housing grants for single moms, Section 8 can provide meaningful long-term rental support.
Public Housing
Public Housing provides affordable rental homes for eligible low-income families, older adults, and people with disabilities through local Public Housing Agencies.
Rent is typically based on household circumstances and income, making the program useful for single mothers who need longer-term housing support rather than short-term emergency assistance.
Emergency Solutions Grants (ESG)
Emergency Solutions Grants fund local organizations that assist people experiencing homelessness or at immediate risk of losing housing.
Support can include emergency shelter, homelessness prevention, rapid rehousing, rental assistance, and related housing-stability services.
ESG funding generally reaches eligible households through local organizations rather than directly from HUD.
It is therefore different from grants for single moms to buy a house, which are more likely to come from down-payment assistance or homeownership programs.
3. Which 6 Homebuying Programs Should Single Moms Explore?
Single moms have several homebuying options that can lower upfront costs and make mortgage qualification easier. Eligibility depends on income, location, credit, and available local assistance.
State and Local Down-Payment Assistance Programs
State and local housing agencies may help eligible buyers cover part of the down payment or closing costs.
Depending on the program, assistance can come as a grant, forgivable loan, deferred-payment loan, or other reduced-cost financing tied to income and location requirements.
For single mothers exploring house grants for single moms, these programs can make homeownership more realistic by lowering the cash needed at closing.
USDA Single Family Housing Direct Home Loans
The USDA Single Family Housing Direct Loan Program serves low and very-low-income applicants in eligible rural areas. It provides payment assistance that can reduce mortgage payments.
For buyers researching grants for single moms for housing, this program is worth comparing with direct assistance because it can reduce upfront costs even though it is still a mortgage rather than grant funding.
USDA Guaranteed Loan Program
USDA’s Guaranteed Loan Program works through approved private lenders and is intended for qualifying households buying or building homes in eligible rural areas.
The program can provide 100% financing with no down payment, while USDA guarantees part of the mortgage to reduce lender risk.
When comparing housing grants for single moms, this option is worth considering even though it is a loan rather than grant money.
FHA Loans
FHA loans can offer a down payment as low as 3.5% for qualifying borrowers, depending on credit and other requirements.
Single-parent status does not provide special FHA eligibility, but the program can still benefit buyers with limited savings or credit challenges.
FHA financing may also be combined with eligible down-payment assistance available in some states or communities.
Fannie Mae HomeReady
Fannie Mae’s HomeReady mortgage is designed for creditworthy low-income borrowers and allows down payments as low as 3%.
It also accepts flexible funding sources such as gifts, grants, and Community Seconds, while current income eligibility is generally limited to 80% of the area median income for the property location.
HomeReady is not one of the home grants for single moms, but pairing it with eligible assistance can reduce upfront costs.
Freddie Mac Home Possible
Freddie Mac’s Home Possible mortgage targets very-low- to low-income borrowers and offers down payments as low as 3%.
Flexible funding sources can help with down payments and closing costs, making the program worth comparing with HomeReady when savings are limited.
Single mothers must still meet normal mortgage, income, property, and underwriting requirements. Home Possible is not free housing assistance, but its lower upfront requirement can work well alongside qualifying state or local down-payment programs.
Find housing grants for single moms and assistance by checking state, local, and federal housing programs. (Image by Unsplash)
4. How to Find Housing Grants for Single Moms and Assistance in Your State?
Local housing help can look very different from one state to another, so searching in the right places matters.
Start With Your State Housing Finance Agency
State housing finance agencies often manage down-payment assistance and first-time buyer programs, with some also offering affordable mortgages.
When looking for grants for single moms to buy a home, check income and property requirements rather than assuming a program is limited by parenting status.
Check Local Housing Authorities and City Programs
County and city housing departments may offer rental assistance, homebuyer education, emergency support, or locally funded grants.
These programs can have smaller service areas and different income limits, so reviewing both city and county resources can uncover options that do not appear in statewide searches.
Use HUD-Approved Housing Counseling Resources
HUD-approved housing counseling agencies can explain local homebuying programs and mortgage options, while also helping applicants understand available assistance.
Counselors can also help applicants compare grants, loans, and down-payment programs before applying, making them especially useful when several local options have different rules.
5. Pro Tips for Single Moms Planning to Buy a Home
Buying a home becomes easier to plan when financing, assistance programs, and everyday household costs are considered together.
A few practical checks can also help single mothers avoid choosing a program that looks affordable upfront but becomes difficult to manage later.
Check more than one assistance source: Compare state and local programs because housing assistance for single moms is often part of broader low-income or first-time buyer programs.
Review the full monthly housing cost: Include the mortgage payment and insurance, then account for taxes, utilities, and other recurring costs.
Strengthen your credit before applying: Paying bills on time and reducing revolving debt can help, while correcting credit-report errors may also improve your application.
Build an emergency fund alongside the down payment: Home repairs and temporary income disruptions can become difficult without savings left after closing.
Ask whether assistance must be repaid: Some down-payment programs are grants, while others provide loans that may be deferred, forgiven, or repaid under specific conditions.
Complete homebuyer education when available: Counseling can clarify mortgage terms, closing costs, budgeting, and program requirements while helping you avoid unsuitable financing.
Get preapproved before choosing a home: Preapproval gives you a clearer price range and shows whether income needs attention before you make an offer.
6. How Can Managing Monthly Bills Lower Living Costs?
Housing expenses are only one part of a household budget, so reducing recurring bills can leave more money available for rent, mortgage payments, utilities, childcare, or savings.
Phone service is one area where eligible households may be able to cut monthly costs through federal assistance.
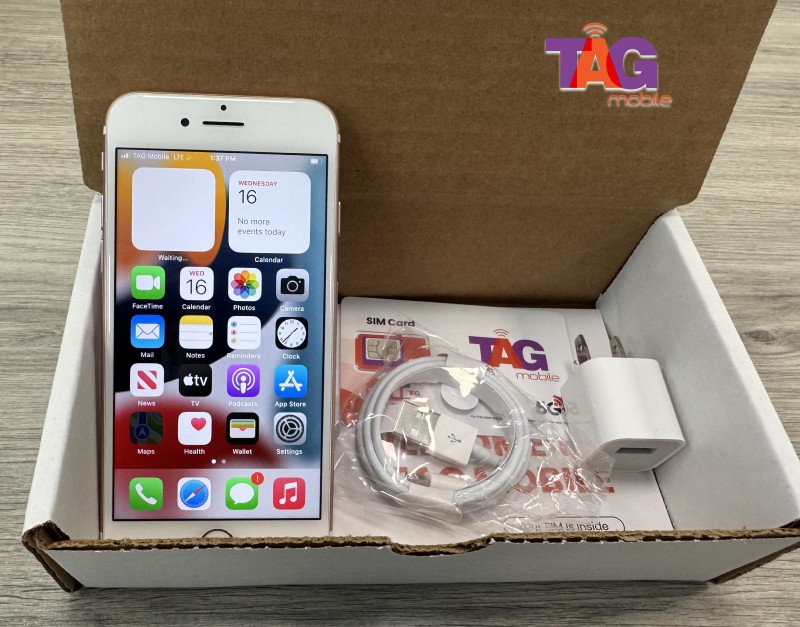
TAG Mobile is a U.S. wireless provider that participates in the federal Lifeline program and offers qualifying customers no-monthly-cost wireless service. The carrier’s Lifeline offerings can include device offers and other communication benefits, depending on location and eligibility.
Lifeline applicants can qualify through household income at or below 135% of the Federal Poverty Guidelines or through participation in a qualifying assistance program. And supporting documentation may be required.
TAG Mobile’s current Lifeline plan includes several features that can help keep communication costs predictable:
Free monthly data, with exact availability varying by state and ZIP code.
Unlimited talk and text for everyday calls and messaging.
Free international calling to more than 200 countries and territories.
Free delivery plus free or discounted phone options for eligible customers, depending on location and inventory.
Nationwide 5G+/4G LTE coverage where available, along with features such as Wi-Fi calling, voicemail, caller ID, call waiting, and 3-way calling.
A device (free or discounted) along with a data plan through TAG Mobile guarantees to elevate your daily life.
Note: Eligibility varies by state and program. Offers depend on availability and qualifications. TAG Mobile operates under the federal Lifeline Program as an Eligible Telecommunications Carrier (ETC). Service is non-transferable and limited to one service per household.
7. Final Thoughts
Finding affordable housing often involves combining several types of support rather than relying on one program alone. Housing grants for single moms may work alongside down-payment assistance, affordable mortgage options, and state or local housing resources.
Comparing eligibility rules, funding limits, and repayment requirements can help families choose suitable support. Those who qualify can also consider TAG Mobile Lifeline service as a way to reduce monthly phone costs.
Share
TAG Blog
Stories, guides, and helpful updates for staying connected.